
Annapolis Valley
Annapolis Valley build: lot equity as the down payment
Can the lot I already own be my down payment on a construction mortgage in the Annapolis Valley?
Can the lot I already own be my down payment on a construction mortgage in the Annapolis Valley?
Yes. A clear lot worth $110,000 against a $420,000 builder contract is 21% equity on a $530,000 project, so the lender funds the build in four draws with no cash down. You pay interest only on money advanced, about $8,177 over a 10-month build at the example rate, and the last draw waits on the 10% lien holdback.
Illustrative example
The situation
- Location
- rural Kings County, Annapolis Valley
- Borrower
- A couple in their fifties who own a two-acre lot outright and hold a fixed-price contract with a Valley builder
- Income
- $134,000 household, one salaried, one pensioned
- Credit
- Both mid-700s; no other debt
- Purchase price
- $530,000
- Down payment
- $110,000
- Mortgage
- $420,000
- Payment at 4.45%
- $2,313 a month
- Down payment $110,000
- Mortgage $420,000
rural Kings County, Annapolis Valley; Annapolis Valley region, where the August 2026 NSAR average was $394,019.
The challenge
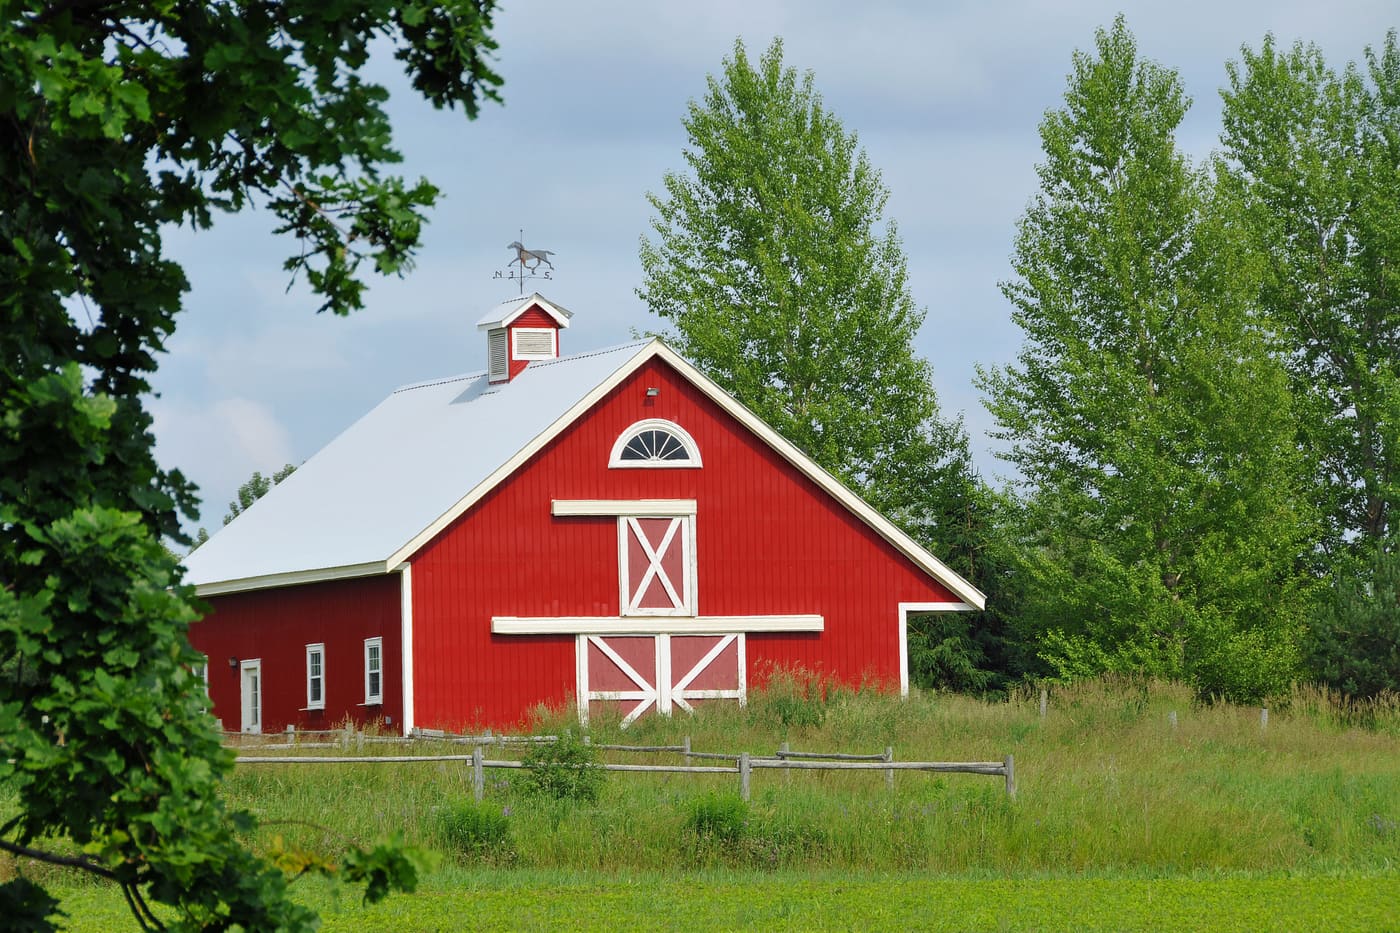
The owners had paid off a two-acre lot outside Berwick and had a fixed-price contract from a local builder. They had little cash beyond a contingency, and the bank branch had asked for a down payment on the build cost as though the land did not exist. The builder wanted to pour the foundation before the ground froze.
What the lender looked at
- The lender appraised the lot and the plans together: $530,000 on completion, lending $420,000, a 79% loan-to-value, so the file stayed uninsured.
- A signed fixed-price contract with a stage schedule matching the lender’s four draws, the building permit, the plans, and the builder’s references and insurance.
- Your money goes in first: with the lot as the equity, the first draw reimbursed the foundation after it was in, so the builder’s contract had to carry that stage.
- Qualifying at 6.45% on the full $420,000 as a 25-year mortgage, $2,801 a month and 30% gross debt service, even though only interest is paid during the build.
- Course-of-construction insurance from the first draw, and on completion a well potability test and the septic installer’s certificate before the final advance.
What was done
The build was set up as a four-draw progress mortgage: Land / start $63,000, Lock-up $168,000, Mechanical and drywall $273,000, Completion $420,000, cumulative. Interest only on the amount advanced, monthly, at the example rate. At completion the lender released the final draw less the $42,000 holdback, which followed once the lawyer’s lien search came back clear after the statutory period, and the loan converted to a 25-year mortgage.
The outcome
Illustrative outcome: about $8,177 of interest across the 10-month build at 4.45% (chartered-bank prime rate, Bank of Canada, 2026-09-30), no cash down payment and no deed transfer tax, since the $1,650 at Kings County’s 1.5% was paid when the lot was bought. On conversion, $420,000 over 25 years at the same rate is about $2,313 a month.
Go deeper
The detail, if you want it
What to take from it
- Land you own is a down payment; make sure the lender appraises it as one before you accept a bank’s request for cash down.
- The builder’s payment schedule must match the lender’s draws, or you will be funding a stage from your own pocket.
- Budget for the holdback: $42,000 arrives weeks after the house is finished, not the day you move in.
- Drill the well and pass the septic inspection early; outside HRM those two sign-offs stall the final draw more than anything else.
How the figures were computed
This is an illustrative example. The people, the property and the outcome are not real; the rules and the arithmetic are. Prices are the August 2026 regional averages from Nova Scotia Association of REALTORS® / CREA monthly statistics, or a stated example price; the deed transfer tax is the municipal rate on the provincial schedule; premiums are CMHC’s published schedule; qualifying uses OSFI’s rule. The contract rate is named in the outcome with its source. Legal, recording and title figures are typical ranges, not quotes.
- www.osfi-bsif.gc.ca: https://www.osfi-bsif.gc.ca/en/supervision/financial-institutions/banks/minimum-qualifying-rate-uninsured-mortgages
- novascotia.ca: https://novascotia.ca/sns/pdf/ans-property-dtt-rates.pdf
- creastats.crea.ca: https://creastats.crea.ca/board/nsar/
How it works
From first call to keys, in four steps
-
A 15-minute call
You say what you’re trying to do and roughly what you earn.
Riley tell you the price a lender will support, the cash you need to close, and what to fix first.
-
Documents and pre-approval
You send the short list through a secure upload link.
Riley package the file and come back with a pre-approval letter and a rate held 90 to 120 days.
-
Lenders, side by side
You read the comparison and pick.
Riley place one application with banks, credit unions and monolines, and show you every answer.
-
Approval, lawyer, keys
You sign with your own local lawyer.
Riley hold the lender, appraiser and lawyer to the closing date.
Why a broker
Licensed, independent, paid by the lender
- Licensed across Atlantic Canada Indi Mortgage operates in all four Atlantic provinces; Riley Oickle, Associate Mortgage Broker, NS 3001134
- $0 broker fee On a standard residential mortgage the lender pays, not you
- 33 lenders, one application Banks, credit unions, monolines; one credit check
Questions people ask
What happens if the build runs past 10 months?
Most lenders allow 12 months of construction, some 18, and grant an extension with a progress report and an updated cost to complete. Interest keeps running on whatever has been advanced: a two-month overrun on the final stage costs about $2,804 more at the example rate.
Does deed transfer tax apply to a house I build on my own land?
No. The tax is charged when a deed transfers, so it was paid once, when the lot was bought: $1,650 at the Municipality of the County of Kings rate of 1.5%. Building on land you already own transfers nothing.
Still unsure? Ask me directly.
If your question isn't here, your situation is probably specific. Fifteen minutes on the phone beats reading another page, and nothing is pulled on your credit.
(902) 298-0218 · 8:00 am to 10:00 pm Atlantic, every day
Your numbers, not the regional average
Send the listing or the statement and a rough income. You get back the same worked arithmetic on your actual figures, in writing, within a business day, at no fee.
(902) 298-0218 · 8:00 am to 10:00 pm Atlantic, every day